If the shortfall requires a job, housing, or business transition, calculate the time available with the financial optionality runway guide before committing to a fixed cost.
When cash is short, the hardest part is not arithmetic. It is deciding which consequence you can tolerate and which one you cannot. A normal monthly budget assumes that the plan can be balanced. A triage plan starts from the opposite premise: the available cash may not cover every claim on it, so the job is to protect the household while buying time to repair the gap.
This guide uses a 30-day control window. That is long enough to include a typical rent or mortgage payment, utilities, minimum debt payments, insurance, transport, food, and one pay cycle. It is short enough to make concrete decisions without pretending you can forecast the next year perfectly.
Start with cash that is actually available
Write down only money that is already in an account or is highly likely to arrive during the next 30 days. Separate it into three lines:
- Available now — checking, cash, and immediately accessible savings.
- Reliable inflows — wages, benefits, or contract payments with a known date and high confidence.
- Uncertain inflows — commissions, sales, reimbursements, tax refunds, or promises that may be delayed.
Do not fund fixed obligations with uncertain inflows on paper. Treat uncertain money as upside. When it arrives, use it to close the highest-priority gap or restore the buffer.
Next, list every expected outflow with its due date, minimum required amount, and consequence of nonpayment. “Credit card — $90” is not enough. Add whether the account is current, whether a promotional rate ends, whether a missed payment triggers a fee or loss of service, and whether the creditor offers hardship options.
Use consequence, not emotion, to set the order
The loudest bill is not always the most important bill. A collection email may feel urgent while a quiet insurance lapse or unpaid utility produces a more serious problem. Rank each obligation using four questions:
- How quickly does harm occur?
- How difficult is the harm to reverse?
- Does nonpayment threaten health, shelter, legal status, insurance, or income?
- Can the provider change the due date, split the payment, or offer temporary relief?
What does the next available dollar protect?
Use the first branch that applies. Move down only after the earlier layer is covered for the current control window.
Fund housing, essential utilities, food, medicine, and necessary care.
Fund transport, childcare, communication, licensing, and required work tools.
Cover affordable minimums, insurance, taxes, and deadlines with serious consequences.
Restore a small buffer, then direct extra cash to the chosen debt or savings priority.
Layer 1: protect the household
The first layer is basic continuity. This usually includes housing, essential utilities, food, medicine, and necessary insurance. The exact order depends on consequence. For example, a utility with an imminent shutoff may outrank a bill that is technically due earlier but has a grace period. A required prescription may outrank a larger discretionary purchase even if the purchase was planned months ago.
Housing decisions deserve special care. Partial payments do not always stop a formal process, and rules vary by contract and jurisdiction. Contact the landlord, servicer, utility, insurer, or agency directly and document what was agreed. Do not assume that sending a token amount creates legal protection.
Layer 2: protect the next paycheck
Cash-flow plans often fail because they protect old obligations while accidentally damaging future income. If a car is essential to work, a repair that keeps it running may be more urgent than an extra credit-card payment. The same logic applies to childcare, a phone used for work, required uniforms, licensing fees, internet access, and the tools needed to complete paid work.
The test is not “Is this work-related?” The test is “Will failing to pay this materially reduce reliable income in the next 30 days?” A premium upgrade, new device, or optional course does not pass that test merely because it is connected to work.
Layer 3: prevent avoidable damage
After essentials and earning capacity, cover affordable minimums and time-sensitive obligations. The goal is to keep a temporary shortage from becoming a larger long-term problem.
Contact creditors before the due date when possible. Ask specific questions:
- Can the due date move to match the pay cycle?
- Is a short hardship plan available?
- Can a fee be waived?
- Will a partial payment count as current?
- What happens to interest, account status, and credit reporting?
- Is the arrangement temporary, and when does normal payment resume?
Record the representative’s name, date, confirmation number, and exact terms. A vague promise is not a plan.
Layer 4: create room to recover
Once the first three layers are covered, use remaining cash to build a small buffer and reduce the structural gap. This is where you pause optional subscriptions, reschedule nonessential purchases, adjust transfers, sell unused items, or add short-term income.
Do not confuse a temporary pause with a permanent solution. Cutting a small subscription cannot repair a major housing or income mismatch. The 30-day plan should reveal whether the gap is:
- Timing — income and bills occur on incompatible dates.
- Variability — income or expenses fluctuate too widely.
- One-time shock — a repair, medical cost, or transition created a temporary deficit.
- Structural — required spending consistently exceeds reliable income.
Choose the repair that matches the gap
| Scenario | Best for | Upside | Main trade-off | Next step |
|---|---|---|---|---|
| Timing gap | Enough monthly income, wrong dates | Often fixable without major lifestyle change | Requires creditor coordination and a small buffer | Move due dates and build one pay-cycle reserve |
| Variable income | Freelance, commission, seasonal work | A base budget can make volatility manageable | Good months must fund future low months | Budget from conservative reliable income |
| One-time shock | Repair, travel, medical, transition cost | The normal budget may recover quickly | Debt can linger after the shock ends | Set a fixed recovery period and payment plan |
| Structural deficit | Recurring shortfall | Early recognition prevents repeated crisis borrowing | Requires a larger housing, debt, expense, or income decision | Build a 90-day restructuring plan |
Worked example: a positive month still runs short before payday
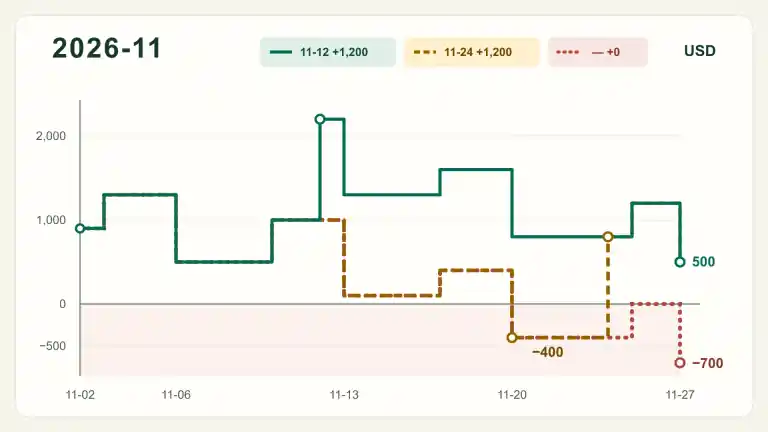
This hypothetical U.S. household example covers November 1–30, 2026, in U.S. dollars (USD). It is not a customer case or a recommended spending level. Opening cash is available after pending commitments; net pay is assumed available on the listed dates. Expense groups are assumed payable on their listed dates. No other transactions, fees, or interest are modeled. In a real calendar, separate each bill and allow for its payment-processing time.
Monthly income is USD 3,600 and required outflows total USD 3,300: a USD 300 surplus. With USD 600 already available, the month-end projection is 600 + 3,600 − 3,300 = USD 900. But a monthly total does not show whether each payment can be funded on time.
| Date | Cash movement | In (+) / out (−) | Projected balance |
|---|---|---|---|
| Nov 1 | Opening available cash, not income | — | 600 |
| Nov 3 | Rent due | −900 | −300 |
| Nov 6 | Food and work transport | −200 | −500 |
| Nov 10 | Net pay available | +1,800 | 1,300 |
| Nov 15 | Food, medicine, and work transport | −500 | 800 |
| Nov 24 | Net pay available | +1,800 | 2,600 |
| Nov 28 | Other essential bills and debt minimums | −1,700 | 900 |
| Nov 30 | Closing projection; no further movements | — | 900 |
The negative figures mean USD 300 is unfunded by November 3, rising to USD 500 by November 6. They are not overdrafts that actually happened, an assumption that a bank will pay the transactions, or permission to miss rent. Later rows continue the arithmetic to expose the timing problem; they do not make the original schedule executable.
One possible response is to ask the landlord, before November 3, whether the USD 900 payment can move to November 11. A request alone changes nothing. Confirm the actual agreement, any fees or interest, payment-processing requirements, account status, and effects on any collection or housing process. Keep the original obligation in the plan unless the changed terms are confirmed; a partial payment does not by itself confirm an agreement or guarantee legal protection.
Only for this alternative calculation, suppose the landlord has agreed to November 11 with no additional charge or adverse status change, and all other assumptions hold. Cash is then USD 600 on November 1; 600 − 200 = 400 on November 6; 400 + 1,800 = 2,200 on November 10; and 2,200 − 900 = 1,300 after rent on November 11. From November 15 onward, balances match the table: 800, 2,600, then 900. The lowest projected balance is now USD 400, and the closing balance remains USD 900.
If the request is declined, a charge applies, or pay arrives late, that alternative is not established: recalculate and keep the unresolved gap visible while protecting essentials and discussing available arrangements. Moving a date addresses timing; it cannot fix a recurring deficit where required spending exceeds reliable income.
The CFPB’s Your Money, Your Goals toolkit includes a bill calendar, a cash-flow budget, and a tool for adjusting payment timing. Use a dated calendar alongside the existing Budget Planner & Expense Tracker for monthly plans and actual transactions. Its interface is currently in English; it does not automatically produce this daily balance projection or verify bank funds. The example is educational U.S.-scope guidance, not individualized financial or legal advice.
Do not let automation make the decision for you
Automatic payments and transfers are useful during stable months. During triage, they can drain the account in the wrong order. Review autopay, savings transfers, investment contributions, subscription renewals, and bill-pay rules. Pause or reschedule only after checking contractual consequences.
Never cancel required insurance or ignore a tax or court obligation simply because it is automatic. The purpose is to regain control of timing, not to erase obligations.
Close the 30-day window deliberately
At the end of the month, compare the plan with what actually happened. Keep four numbers:
- Reliable income received
- Required spending paid
- New debt added
- Cash remaining
If the month ended without new debt and with all priority layers protected, the triage plan worked. The next step is to turn it into a normal monthly budget and start the first emergency-fund tier. If the gap remains, do not repeat the same month with more optimism. Move to a longer plan: hardship negotiation, debt sequencing, income restructuring, relocation, or another major decision.
Turn the page into action
Complete your 30-day triage
- List available cash, reliable inflows, and uncertain inflows separately.
- Record every obligation with its due date, minimum, and consequence of nonpayment.
- Protect essentials and the ability to keep earning first.
- Contact any creditor or provider before a payment will be missed.
- Pause optional transfers that would create a later shortfall.
- Track actual results and choose the next-cycle repair before the month ends.
Evidence to action
Methods and evidence
Methods used
- Emergency runway
runway months = liquid reserves ÷ essential monthly outflow
Related data series
- Economic Well-Being of U.S. HouseholdsCataloged; automatic updating is not active yet.
Next actions
Structured datasources.jsonformulas.jsonsystems.json
Evidence
Sources
- Your Money, Your Goals toolkit
cfpb-your-money-your-goalsConsumer Financial Protection BureauAccessedOctober 14, 2026
- Economic Well-Being of U.S. Households in 2025 — Executive Summary
federal-reserve-household-wellbeing-2025Board of Governors of the Federal Reserve SystemAccessedAugust 18, 2026
- Saving for the Unexpected and Your Future
fdic-saving-unexpectedFederal Deposit Insurance CorporationAccessedAugust 18, 2026
Common questions
Frequently asked questions
What should I pay first when I cannot cover everything?
Fund the obligations with the fastest and most serious consequences first: basic housing, utilities, food, essential medicine, and the costs required to keep earning. Then protect minimum contractual payments, insurance, and deadlines while contacting creditors before accounts become more difficult to repair.
Should I pay extra on debt during a cash-flow emergency?
Usually not until essentials, minimum payments, and a small shock buffer are covered. An extra debt payment is useful only when it does not force you to borrow again for food, transport, medicine, or a predictable bill.
How long should a cash-flow triage plan last?
Thirty days is a useful first control window because it captures one monthly bill cycle. At the end of the window, convert the temporary plan into a repeatable budget or escalate to a longer hardship, debt, or income plan.